Distinguishing Two Forms of Coherence Arguments in Economic Choices
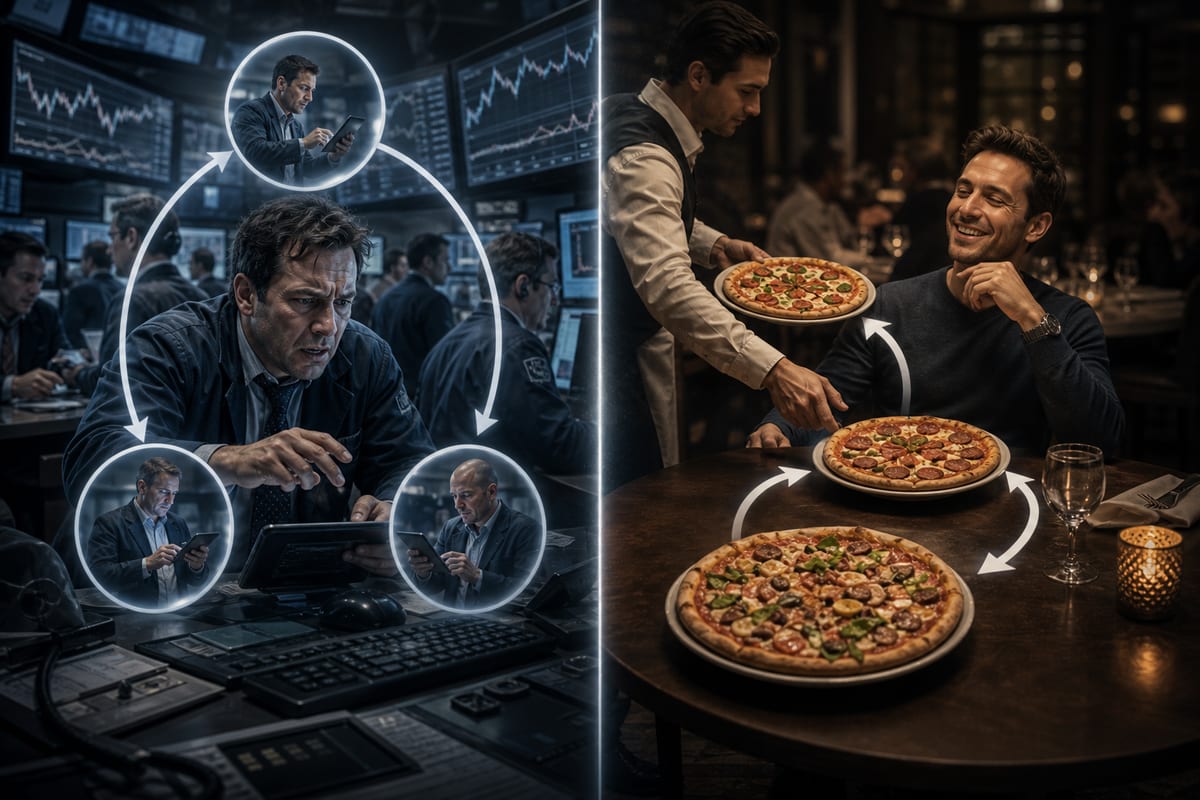
The same reasoning can cover two distinct mechanisms: avoiding errors that "drain" money and making choices that sacrifice wealth for something else. The author argues that the first pressure is strong, while the second is much more conditional. Confusing them leads to poor intuitions, including when "solving for equilibrium" in markets or in the development of AI systems.
Equilibrium does not distinguish between loss by error and intentional sacrifice
Grouping two effects of "coherence arguments" masks a dissymmetry of strength: one dominates the other. This confusion facilitates argumentative slippages of the motte-and-bailey type. "Solving for equilibrium" is often relevant for loss by error (Thing A), but rarely serves as a good starting point for intentional loss (Thing B). In the real world, Thing A is frequently decisive: there are no obvious large arbitrages today, and the majority of assets are in the hands of decision-makers whose investment choices are coherent and not "bookable" in a Dutch manner. Hence, the relevance of equilibrium for sketching predictions on this dimension. Conversely, Thing B weighs little in a decisive manner. If one were to push the equilibrium reasoning to its limits, one would wrongly predict that almost all wealth would belong to agents who never spend for pleasure, never divest from companies deemed unethical, and never accept trade-offs unfavorable to wealth maximization.
One label covers two dynamics
Behind the coherence argument, two phenomena are often wrongly aggregated. In one, actors deliberately accept losing a fraction of their wealth to gain more of what they value. In the other, the loss is accidental. The reasoning does not distinguish between these cases as it judges behaviors, indifferent to motivations, and would apply in the same way to a market of trading algorithms without motivations. However, these dynamics do not unfold in the same manner, and one generally produces a much stronger effect. In the three areas considered, the salient pressure is primarily to act "well" according to one's own criteria, as if one had self-coherent desires. The tendency to impose a long-term consequentialist orientation appears only weakly or conditionally, and can coexist with other forms of preferences, including myopic ones. This ambiguity makes these arguments pedagogically tricky and fuels confusion between the strong effect and the weak effect.
Le brief IA que les pros lisent chaque soir
Les 7 actus IA du jour, décryptées en 5 min. Gratuit.
Inclus dès l'inscription : notre sélection des meilleurs guides & comparatifs IA.
Choisissez votre rythme
Gratuit · Pas de spam · Désabonnement en 1 clic
Thing A: exploitable incoherence and its consequences
The first dynamic concerns losses by error. A classic example: buying each step of a Dutch book because each exchange seems wise in isolation, only to discover the loss at the end of the cycle. This phenomenon is central, and identifying it as a coherence defect is appropriate here. A person can be so incoherent that it becomes difficult to define what they truly want, even if it is reasonable to assume they did not intend to lose without compensation. Transposed to the stock market, this framework suggests that circular preferences systematically transfer value to non-circular agents. More broadly, wealth concentrates over time among those whose behavior is coherent, to the detriment of others, such that the market becomes, all else being equal, dominated by goal-oriented and self-coherent behaviors. The architecture of this argument is technically sound.
Thing B: losing to gain something other than money
The second dynamic concerns intentional losses. Actors know what they are doing and accept it. An example presented elsewhere illustrates a customer who, at a restaurant, pays $0.01 to switch from an onion pizza to a pineapple one, then $0.01 from pineapple to mushrooms, then $0.01 from mushrooms back to onions, and so on. Taken as such, this cycle is described as suboptimal assuming the person aims for the best final pizza and chooses accordingly. But if their preference is actually to tease the waiter, the same pattern corresponds to satisfying their own preferences: they are buying cheap entertainment. The analogy holds for someone who finances expensive parties rather than reinvesting. Over time, all else being equal, their relative share of wealth decreases, without contradicting their goals.
Three areas, two pressures: strong self-coherence, conditional long-term
The author extends this diagnosis to three areas: competition in markets, reflection and self-modification by AI, and AI training algorithms. In each, he identifies two distinct pressures: a strong pressure to act self-coherently, and a distinct pressure to prioritize distant final outcomes with indifference to the rest. This second pressure appears weaker and/or more conditional than the first. By merging them under a single label of "coherence arguments," one commits, according to him, a classification error that muddles the analysis and the predictions one claims to derive from it.
Brief IA — L'actualité IA en français
L'essentiel de l'actualité de l'intelligence artificielle, décrypté et expliqué chaque jour.